Leadership Transitions: A Test of Stability vs. Reinvention
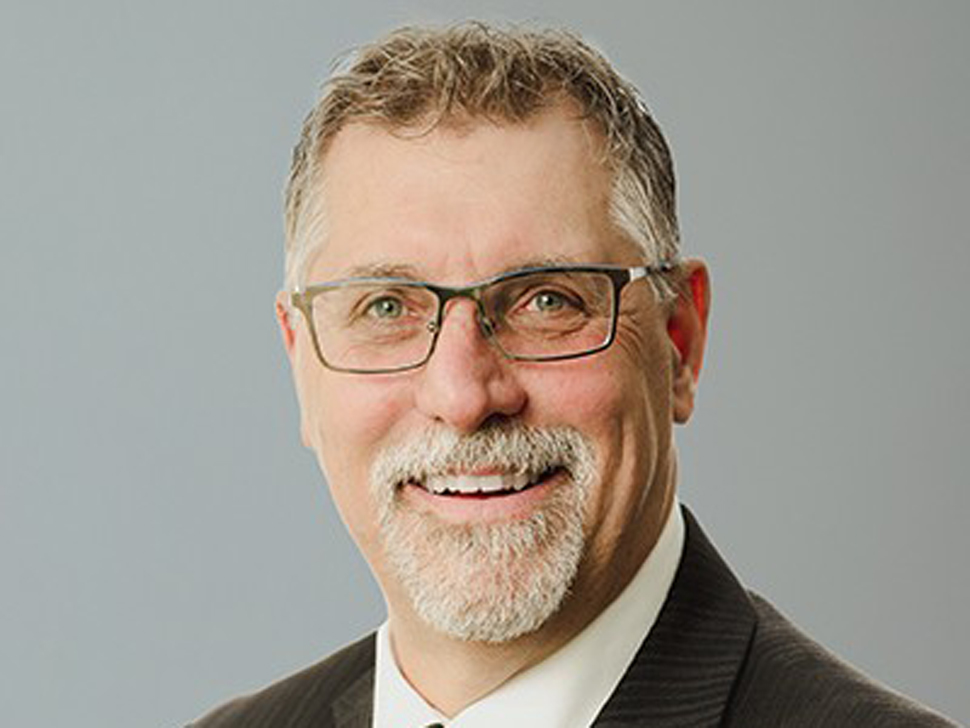
When Steinbach Credit Union (SCU) announced James Gosselin as its interim CEO, the move felt less like a routine leadership shuffle and more like a deliberate gamble on continuity. After all, Gosselin isn’t just another suit in a boardroom—he’s a 30-year veteran of the institution, a living archive of its culture and values. But here’s the question that keeps me up at night: In clinging to the familiar, is SCU safeguarding its legacy or stifling its future?
The Insider’s Advantage: Stability or Stagnation?
Let’s unpack the board’s logic. By promoting Gosselin, SCU is betting that deep institutional knowledge will smooth the transition. Maria Reimer, the board chair, called his appointment a "proven track record"—code for "we know what we’re getting." But this raises a deeper question: Why fix what isn’t broken? SCU’s financial health seems solid, yet the abrupt exit of former CEO Curtis Wennberg (under a "mutual agreement") hints at tensions beneath the surface. Was his departure a strategic pivot, or a quiet acknowledgment of misaligned visions? Gosselin’s dual role as Chief Corporate Sales Officer adds intrigue—will his focus on sales-driven leadership prioritize member satisfaction or quarterly metrics?
The Curious Case of the 12-Month Interim Term
A 12-month interim term? That’s unusually long. Most organizations treat interim roles as brief bridges to stability. But SCU’s 12-month timeline suggests either a methodical search for a permanent CEO or a tacit audition for Gosselin himself. Personally, I think this reflects a board caught between two worlds: wanting fresh ideas but fearing disruption. By extending the interim period, they’re buying time to assess whether Gosselin’s experience can evolve into visionary leadership—or if they’ll need an outsider later. It’s a high-wire act with no safety net.
What Few Are Asking: The Community Impact
SCU’s identity as a credit union—rooted in community—is central to this story. Gosselin’s emphasis on "exceptional service to our members" sounds noble, but let’s dissect it. In an era where fintech startups and big banks are poaching customers with AI-driven convenience, is doubling down on tradition enough? What many people don’t realize is that credit unions like SCU face a paradox: their community-first ethos is both a strength and a vulnerability. Will Gosselin’s leadership accelerate SCU’s adaptation to digital banking trends, or will nostalgia for face-to-face service become a liability?
The Unspoken Elephant: Why Now?
Curtis Wennberg’s exit in August 2025—barely a year after joining—deserves scrutiny. The board’s vague "mutual agreement" language is a red flag. Did Wennberg clash with the board over strategic priorities? Was his vision for growth too aggressive, or not aggressive enough? And why keep him on as a senior advisor until 2026? This arrangement feels like a corporate ceasefire, a way to avoid public drama while hashing out differences privately. But it also creates ambiguity: How much influence will Wennberg retain, and could that cloud Gosselin’s authority?
A Broader Bet on Continuity
SCU’s decision mirrors a trend in organizations clinging to insiders during turbulent times. Think of how legacy automakers promote engineers to CEO instead of tech disruptors, or how newspapers appoint veteran editors amid digital upheaval. The logic is comforting: Those who built the empire can best defend it. But what this overlooks is that today’s challenges demand hybrid leaders—people who can honor tradition while dismantling outdated systems. Gosselin’s career in corporate lending is impressive, but will it equip him to navigate the existential threats facing credit unions? Cybersecurity risks, fintech competition, and shifting member expectations aren’t problems of the past; they’re storms brewing on the horizon.
Final Thoughts: The Real Story Isn’t the CEO
Here’s the contrarian take: The bigger story isn’t Gosselin or Wennberg. It’s the board’s appetite for risk. By choosing continuity, they’ve signaled a preference for incremental progress over reinvention. In the short term, this might stabilize SCU’s reputation. But if the credit union sector is to survive the next decade, it needs leaders who aren’t just custodians of trust but architects of transformation. Will Gosselin surprise us by embracing disruption, or will SCU become a cautionary tale of playing it safe? Only time will tell, but the stakes are higher than most realize.